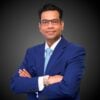


In an exclusive interview with CanadianSME Small Business Magazine, Paul Casey, Director of Small Business at Meridian Credit Union, shares his perspective on helping Canadian entrepreneurs build stronger, more adaptable businesses in an evolving economic environment. With extensive experience supporting small and medium-sized businesses, Paul discusses why strategic planning, financial awareness, and trusted advisory relationships are essential for long-term success.
Interview By SK Uddin
As Meridian’s Director of Small Business, Paul Casey provides strategic leadership for Meridian’s province-wide Small Business Division, working closely with teams of specialized Small Business advisors in every corner of Ontario. His focus is on empowering Meridian leaders to deliver exceptional advice and value to Meridian’s fast-growing SME business Members, who are important contributors to the economic vitality of communities across Ontario. Before joining Meridian, Paul held several senior leadership positions with BDC, including VP, Financing and Consulting for SW Ontario.
What’s your big picture advice for business owners/operators when it comes to planning in uncertain times?
Uncertainty is something every business owner will face. While no one can predict exactly what’s around the corner, business owners can put themselves in a stronger position by focusing on what they can control.
That starts with understanding the fundamentals of your business, your cash flow, profitability and customer demand—but it also means taking time to think beyond today’s challenges. The businesses that tend to navigate uncertainty best are those that balance day-to-day decision-making with a longer-term view of where they want to go.
It’s also important to seek advice before it’s needed. Whether it’s your accountant, lawyer, industry peers or financial partner, having trusted people around you who understand your goals can help you navigate challenges and identify opportunities you might otherwise miss.
Ultimately, planning isn’t about predicting the future. It’s about building the confidence and flexibility to adapt as conditions change.
What are the top 3 datapoints or business health indicators business operators should be taking a hard look at?
1. Cash Flow
Cash flow is often the clearest indicator of a business’s financial health. Revenue can look strong on paper, but understanding what’s coming in, what’s going out and when those transactions occur is critical to managing day-to-day operations and planning for growth.
2. Profit Margins
In a higher-cost environment, businesses need to understand where their profits are coming from and whether rising expenses are putting pressure on margins. Regularly reviewing pricing, labour costs and operating expenses can uncover opportunities to improve efficiency and profitability.
3. Working Capital
How quickly are receivables being collected? Is inventory moving efficiently? Do you have access to enough liquidity if business conditions change unexpectedly? These metrics provide valuable insight into how resilient a business is and how prepared it is for growth opportunities or economic shifts.
Together, these indicators help tell the full story of a business’s health—not just where it is today, but where it may be headed next.

Talk to me about accessing capital and how to know when is the right time to seek and/or accept financing?
One of the most common misconceptions among entrepreneurs is that financing should only be considered when there’s an immediate need.
In reality, the best financing conversations often happen well before a business requires capital. Whether you’re planning to hire staff, purchase equipment, expand operations or pursue a new opportunity, exploring your options early gives you more flexibility and time to make informed decisions.
The right time to seek financing is when there’s a clear purpose and a strong understanding of how that investment will help move the business forward. Financing should support a broader strategy, whether that’s creating efficiencies, increasing capacity or positioning the business for future growth.
It’s also important to remember that every business has a unique story. While financial performance matters, understanding a business’s goals, opportunities and challenges often leads to a more meaningful conversation about capital and long-term success.
What do you wish more business owners/operators would speak with their financial institution about—and why?
Their future plans.
Many business owners initially approach their financial institution with a specific need, such as financing or day-to-day banking. Yet some of the most productive conversations happen before a transaction is ever needed.
Whether it’s succession planning, expansion into new markets, managing cash flow, investing in technology or preparing for future opportunities, sharing those plans early allows for more thoughtful advice and better long-term planning.
The more context a business owner is comfortable sharing, the easier it is for their advisors to understand the bigger picture and help identify solutions or opportunities that may not have otherwise been considered.
Strong relationships are built through ongoing conversations, not just transactions.
What are the biggest challenges most Canadian SMEs face right now?
Many small and medium-sized businesses continue to face a combination of pressures rather than a single challenge.
The cost of doing business remains high, with labour, insurance, utilities and operating expenses continuing to impact margins. At the same time, many businesses are adapting to changing customer expectations and ongoing economic uncertainty.
Talent attraction and retention also remain key concerns. Across many sectors, business owners are looking for ways to attract skilled employees while balancing costs and maintaining growth.
Another challenge is simply finding the time to think strategically. Many entrepreneurs are managing multiple priorities every day, making it difficult to step back and focus on long-term planning.
Despite these challenges, Canadian business owners continue to demonstrate remarkable resilience, adaptability and innovation—qualities that have always been hallmarks of entrepreneurial success.
Are there any new government initiatives to support SMEs that you feel more business owners should take advantage of—or at least explore with their financial partners?
One program worth exploring is the BDC Accelerator Loan Program, which is helping expand access to capital for entrepreneurs and businesses that may not always fit traditional lending models.
Programs like this can provide additional flexibility for businesses looking to invest in growth, manage working capital needs or pursue opportunities that might otherwise be difficult to finance. For newer businesses and entrepreneurs from underrepresented groups, these programs can be especially valuable.
At Meridian, we’re proud to be one of a select group of financial institutions participating in the program. As the largest credit union in Ontario, Meridian combines the benefits of programs like BDC Accelerator with relationship-based banking, personalized advice, and local decision-making. This allows us to help business owners access financing solutions that support their unique growth objectives while providing the guidance and expertise needed to navigate today’s increasingly complex business environment.
More broadly, I encourage business owners to regularly ask about government-backed financing programs, grants and advisory resources. Many entrepreneurs are focused on running their business and may not realize what support is available.
A conversation with a trusted financial partner can often uncover opportunities that align with a business’s goals and stage of growth.
What are the biggest lessons you’ve learned from Meridian’s SME clients?
One of the biggest lessons I’ve learned is that successful businesses are rarely built in isolation.
The entrepreneurs who thrive over the long term are often those who stay connected—to their customers, employees, communities and trusted advisors. They understand their numbers, but they also understand the importance of relationships and remain open to learning and adapting as circumstances evolve.
I’ve also seen that resilience comes in many forms. Some businesses succeed by innovating, others by staying disciplined and focused on their core strengths. What they all have in common is a willingness to evolve when conditions change.
Perhaps most importantly, I’ve been reminded time and again of the role small businesses play in strengthening our communities. They create jobs, support local initiatives, foster innovation and contribute to the economic well-being of the regions they serve. When local businesses succeed, the benefits extend far beyond the business itself.
Disclaimer : The views and opinions expressed in this interview are those of the guest and do not necessarily reflect the official policy or position of Black Business Magazine or its affiliates. The magazine is committed to supporting Black entrepreneurs and fostering conversations that promote inclusion and economic empowerment.